


Share This Article
“A tax credit designed for low-income renters must actually be usable by low-income renters. Today, an older New Yorker can do everything right, qualify entirely based on her income, and still walk away empty-handed simply because she lives in a market-rate apartment.”
As a CPA practicing in Manhattan, I spend every tax season navigating the finer points of New York’s tax code to help individuals and small businesses keep more of what they earn. Over the years, I have seen firsthand how well-intentioned policies can look great on paper but fall short in practice. A prime example is New York’s real property tax circuit breaker credit—a policy meant to protect low-income renters that decades of legislative neglect have put out of reach for most of the renters it was meant for.
The core issue is a single number that has remained completely frozen since at least 2000: $450. Under current state tax law, if a tenant’s average monthly rent exceeds $450—excluding charges for heat, gas, electricity, furnishings, or board—they receive absolutely nothing. It does not matter if their income is zero or if their rent swallows every dollar they have. Once their monthly rent crosses that $450 threshold, the credit is gone.
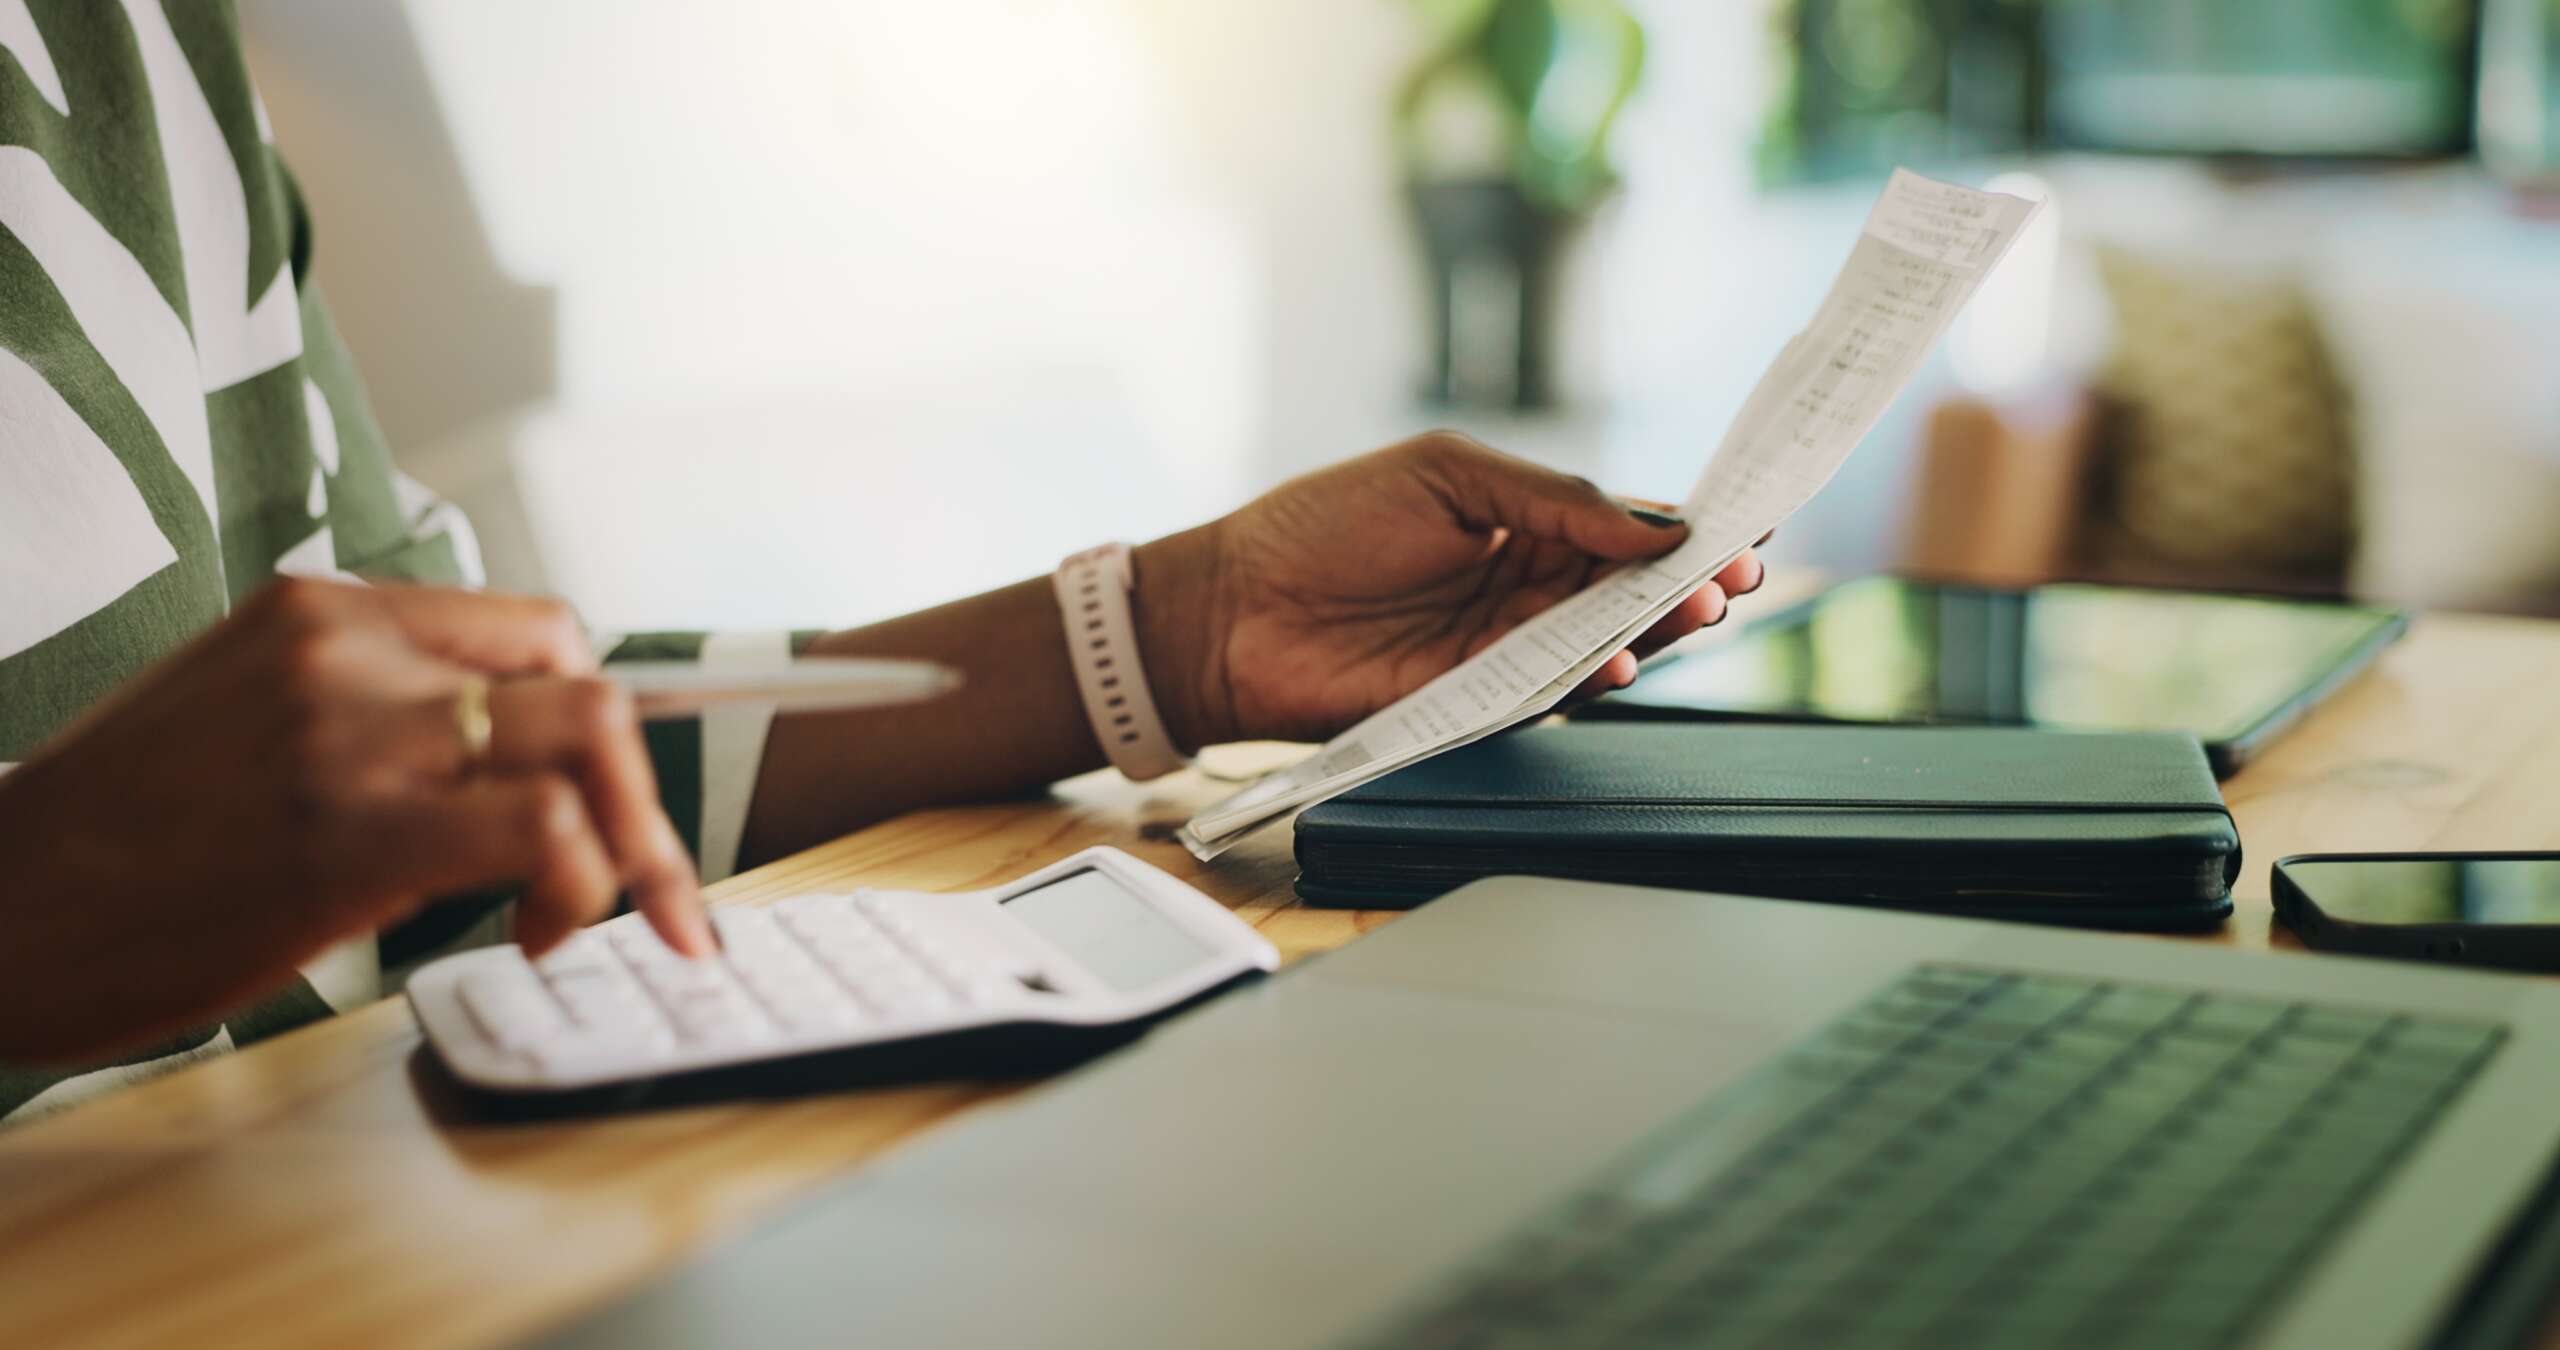
Consider a hypothetical retiree living in the Bronx. She is 66 years old, single, and relies entirely on a fixed income of $24,000 a year from Social Security. Until recently, she was completely locked out of the credit because the state counted all Social Security payments toward its strict $18,000 income limit. Thankfully, Albany corrected this in the 2025-26 state budget. Starting in tax year 2025, the income test finally aligns with federal adjusted gross income (AGI). Because federal law does not tax her Social Security, her federal adjusted gross income is zero. On paper, she passes the income test perfectly.
Yet, she still receives nothing. Why? Because her rent is more than $450 a month. If her rent met that outdated cap, the circuit breaker would provide her with a critical credit of up to $375 a year—real money for an older New Yorker on a fixed budget. Instead, the law updates the income rules to reach her, only to slam the door in her face with a frozen rent restriction.
The underlying logic of a circuit breaker credit is sound. Renters pay property taxes indirectly because landlords pass those costs down through monthly rent. New York law codifies this by treating 25 percent of a tenant’s rent (not counting heat, gas, electricity, furnishings, or board) as their property tax share, offering a credit when that burden becomes too heavy relative to their income. The income limit remains $18,000, as it has been since at least tax year 1993, according to the Tax Department’s report on that year, while the $450 rent cap appears at least as far back as the 2000 filing instructions.
The arithmetic behind that $450 figure reveals just how disconnected the law has become from modern reality. Federal law sets rent in public housing at 30 percent of a family’s monthly adjusted income, or one of two alternatives, whichever is highest. Thirty percent of New York’s $18,000 state income limit is exactly $5,400 a year, which breaks down neatly to $450 a month.
While no official legislative document I have found says that this is why the $450 cap was chosen, the numbers line up. The tragic irony is that this cap describes a rental rate that federal standards already consider affordable. It shuts out every tenant whose rent is above that level, however little they earn, including those forced to spend far more than 30 percent of their meager earnings on a place to live.
What happened over that quarter-century is documented in the state’s own open data catalog. In tax year 2000, New York City renters filed 185,320 claims for this tax credit. By 2024, that number plummeted to just 93,882—a staggering 49 percent drop. Statewide, counting homeowners and renters together, total claims collapsed from 298,736 down to 114,413, a 62 percent decline. While raw statistics cannot tell us the individual story behind every missing claimant, one thing is clear: over the same years, the two numbers that determine eligibility stayed locked in place.
Albany has already proven it has the political will to start fixing this system, but leaving the job half-done helps no one. Two active bills in the current legislative term attempt to solve the crisis. Assembly Bill A7652, sponsored by Assemblymember Steve Stern, would lift the rental cap from $450 to $1,000. Meanwhile, Senate Bill S1147, sponsored by Sen. Andrew Gounardes, proposes creating an entirely separate credit specifically tailored to New York City renters with no rent cap at all.
Unfortunately, both bills are currently languishing in their respective committees—Ways and Means in the Assembly, and Budget and Revenue in the Senate. When the two-year legislative term concludes on Dec. 31, both bills will officially die.
This leaves the upcoming state budget as the most practical vehicle for meaningful change. The path forward does not need to be overly complicated. First, lawmakers must raise the rent cap to mirror the actual, baseline housing costs that low-income tenants face in today’s market. Second, they must tie this cap to a reliable cost-of-living index so it cannot quietly freeze for another generation.
Finally, they must explicitly preserve the 2025 budget fix that excludes untaxed Social Security. This last step matters: A7652, drafted before that budget passed, would return to an income test that counts Social Security, though with a much higher limit of $100,000.
A tax credit designed for low-income renters must actually be usable by low-income renters. Today, an older New Yorker can do everything right, qualify entirely based on her income, and still walk away empty-handed simply because she lives in a market-rate apartment. albany
Albany has already completed the heavy lifting by reforming the income definitions. Fixing the archaic $450 rent cap is the easy half of the equation. It is time for the legislature to finish the job.
Myung Keon Kim is a CPA in Manhattan who prepares tax returns for individuals and small businesses in New York, New Jersey and Connecticut.